


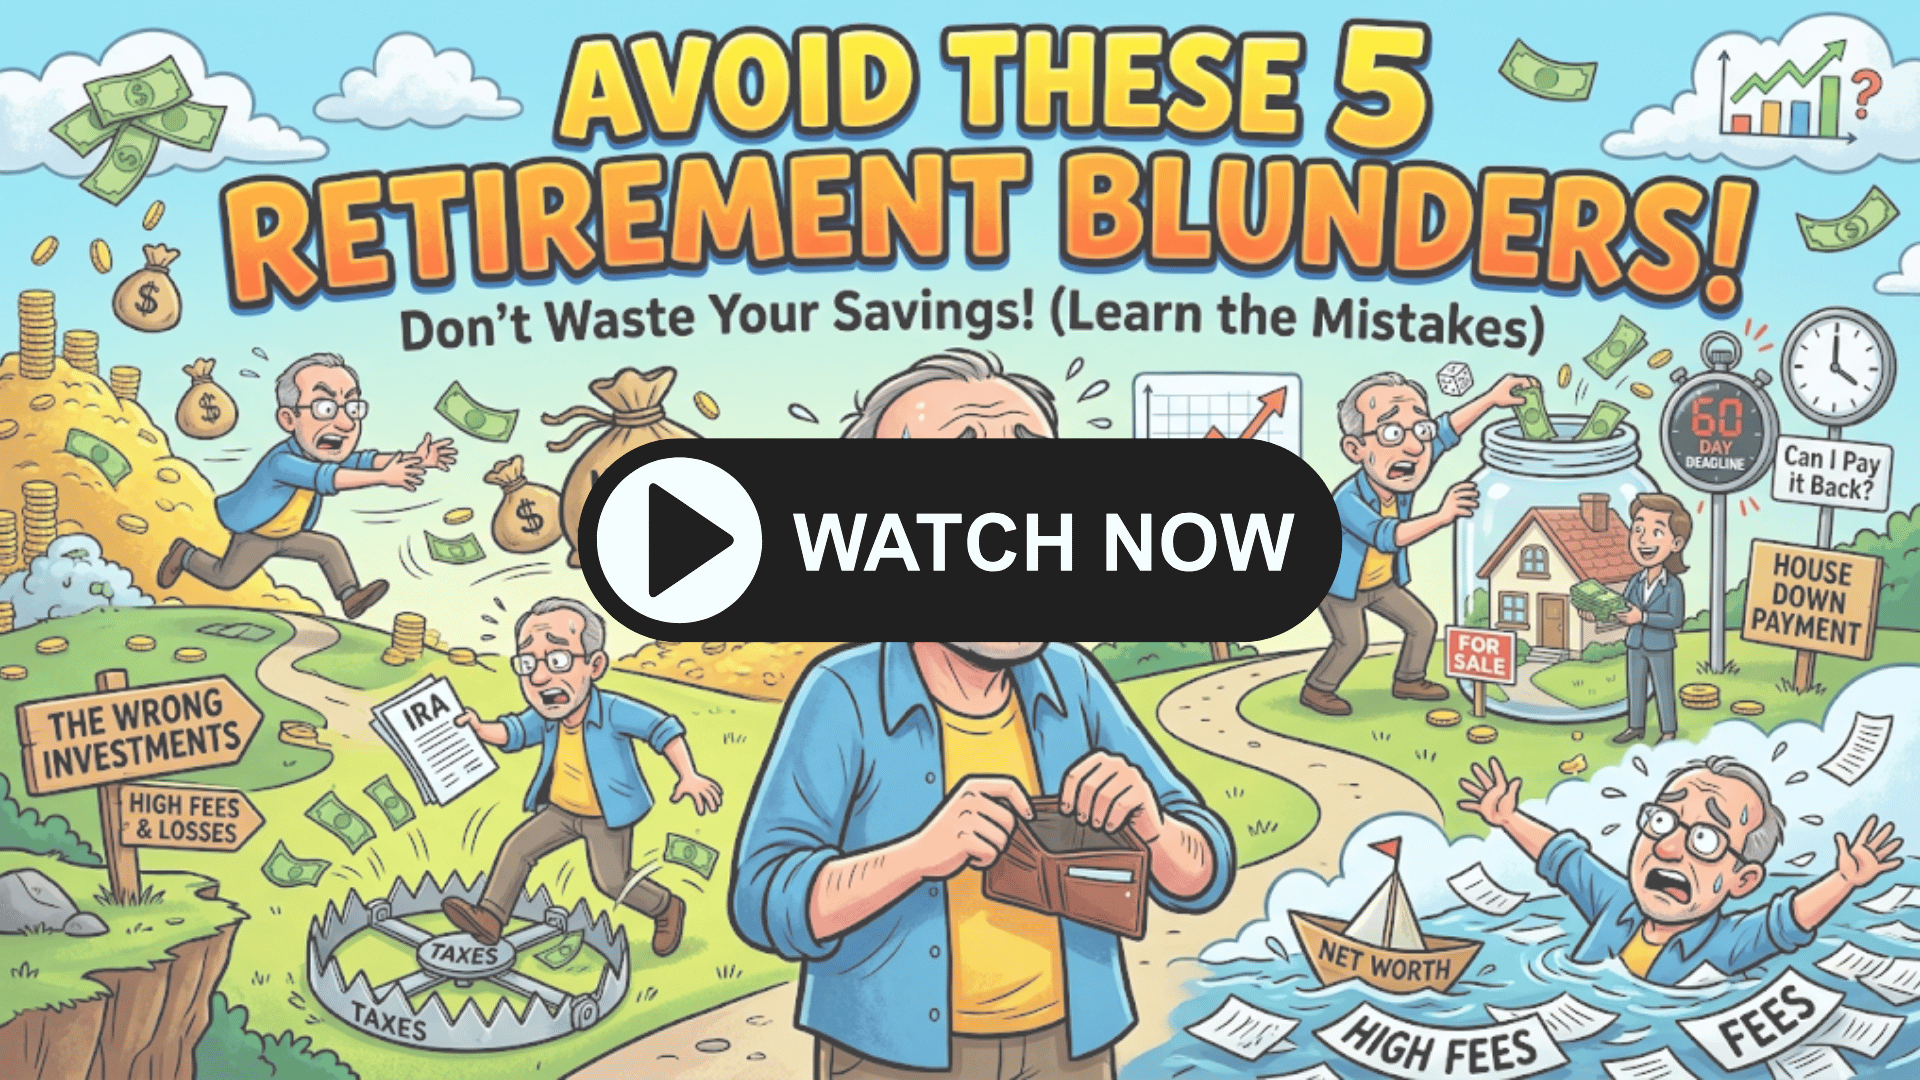
Navigating retirement distributions and tax planning involves strict IRS regulations where a single misstep can trigger immediate taxation, steep penalties, and permanent loss of tax-advantaged growth.
Understanding these five common retirement blunders can help you protect your net worth and make informed decisions with your wealth.
1. Taking Cash Distributions on a Non-Spouse Inherited IRA
When inheriting an IRA as a non-spouse beneficiary (such as an adult child), the IRS enforces strict distribution guidelines.
The Trap: If you request a payout check payable to yourself with the intent to redeposit it into an inherited IRA elsewhere, the IRS does not allow a 60-day rollover window for non-spouse beneficiaries. The full withdrawal becomes an immediate taxable event.
The Solution: Always execute a direct, trustee-to-trustee transfer. The funds must move directly between financial institutions into a properly titled Inherited IRA account.
2. Misusing the 60-Day Rollover Rule (The "Bridge Loan" Gamble)
The IRS permits an indirect rollover, where you receive account funds directly and have 60 days to redeposit them into an eligible retirement account.
The Trap: Attempting to treat an IRA withdrawal as a short-term bridge loan—such as making a down payment on a new property while waiting for a previous home to sell—carries extreme risk. If the real estate sale stalls past day 60, the entire amount becomes fully taxable, plus potential early withdrawal penalties. Additionally, the IRS strictly enforces a one rollover per 365-day rule across all your IRAs.
The Solution: Avoid using retirement accounts for short-term liquidity needs. Use direct institutional rollovers for routine account consolidations to prevent tax-withholding shortfalls and missed deadlines.
3. Choosing the Wrong Spousal Inherited IRA Election
Surviving spouses have options that non-spouse beneficiaries do not: they can roll inherited IRA assets into their own IRA or maintain the account as a beneficiary.
The Trap: If a surviving spouse is under age 59½ and immediately elects to treat the account as their own, any subsequent distributions taken for emergency living expenses will be subject to a 10% early withdrawal penalty on top of ordinary income taxes.
The Solution: Evaluate your liquidity timeline. Leaving the funds in an Inherited IRA allows penalty-free access under age 59½, or you can split the balance between an inherited beneficiary account and your own IRA based on cash flow projections.
4. Executing Roth Conversions Too Early (and Ignoring IRMAA)
Converting pre-tax dollars into a Roth IRA can build tax-free compounding, but timing dictates efficiency.
The Trap: Performing large conversions in the first quarter leaves no margin for unexpected taxable income later in the year (such as large severance packages, business sales, or capital gain distributions), which can push your income into a much higher marginal bracket. Furthermore, higher Modified Adjusted Gross Income (MAGI) can trigger higher Medicare Part B and Part D premiums two years later through IRMAA surcharges.
The Solution: Model Roth conversions later in the fourth quarter when your full-year tax picture, income thresholds, and IRMAA brackets are clearly established.
5. Forfeiting Net Unrealized Appreciation (NUA) on Company Stock
If you hold highly appreciated company stock inside an employer-sponsored 401(k), the IRS offers a distinct tax strategy known as Net Unrealized Appreciation (NUA).
The Trap: Automatically rolling your entire 401(k) into a Traditional IRA permanently invalidates the ability to use NUA. Once rolled over, future distributions are taxed as ordinary income rather than lower long-term capital gains rates.
The Solution: Review the cost basis of your employer stock before initiating any plan rollover. Distributing the shares into a taxable brokerage account allows you to pay ordinary income tax only on the cost basis, while the appreciation qualifies for preferential long-term capital gains treatment upon sale.
Plan Before You Move Funds
Retirement tax rules are complex and often irreversible once paperwork is processed. Before initiating any rollovers, conversions, or distributions, consult with your advisory and tax team to ensure each action aligns with your broader financial plan.
IRS References Referred To:
Primary Statutory References (Internal Revenue Code)
IRC § 408(d)(3)(A)(i): Governs rollovers from an Individual Retirement Account (IRA) to another IRA or eligible retirement plan. It establishes the requirement that the distributed amount must be paid into the receiving plan or account not later than the 60th day after the day the individual receives the payment or distribution.
IRC § 408(d)(3)(B): Defines the one-rollover-per-year limitation, prohibiting a tax-free rollover if the individual received a distribution from an IRA within the preceding 1-year (365-day) period that was rolled over tax-free (codified further by Bobrow v. Commissioner, 2014, and IRS Announcement 2014-32).
IRC § 402(c)(3): Governs eligible rollover distributions from employer-sponsored qualified retirement plans (such as a 401(k) or 403(b)) to an eligible retirement plan, setting the same 60-day deadline from the date of receipt.
IRC § 408(d)(1): Mandates that any amount paid or distributed out of an Individual Retirement Account (IRA) must be included in gross income by the payee or distributee under the rules of IRC § 72. Because an IRA is a tax-exempt trust under IRC § 408(e), assets held within an IRA lose their underlying character (e.g., dividends, tax-exempt interest, or capital gains). Distributions are categorically classified as ordinary income.
IRC § 402(e)(4)(A) & (B): Provides the statutory exclusion from gross income for Net Unrealized Appreciation (NUA) in employer securities. To qualify for NUA treatment, the securities must be part of a lump-sum distribution directly from an eligible employees' trust described in IRC § 401(a).
IRC § 402(c)(1): Dictates that if an eligible rollover distribution (including employer securities) is rolled over into an eligible retirement plan such as a traditional IRA, the distribution is excluded from gross income in the year of rollover. However, because the shares are now subject to the distribution regime of IRC § 408(d)(1), the specific NUA exclusion under § 402(e)(4) is extinguished, and subsequent distributions cannot claim capital gains rates.
IRS Publications & Administrative Guidance
IRS Publication 590-A (Contributions to Individual Retirement Arrangements): Chapter 1, under "Rollover From One IRA Into Another" and "Can You Move Retirement Plan Assets?", explicitly details the 60-day time limit, the mechanics of receiving a distribution directly, and the once-per-year limitation.
IRS Publication 575 (Pension and Annuity Income): Covers the 60-day rollover rules and mandatory 20% federal tax withholding rules associated with indirect rollover distributions paid directly to plan participants.
IRS Tax Topic No. 413 (Rollovers from Retirement Plans): Summarizes the 60-day rule: "If a plan pays you an eligible rollover distribution, you have 60 days from the date you receive it to roll it over to another eligible retirement plan."
Compliance & DisclosureThis material is provided for educational and informational purposes only and does not constitute personalized investment, legal, or tax advice. Investment advisory services are offered through Team Wealth & Tax Advisors, an SEC-registered investment adviser. Tax rules and strategies vary based on individual circumstances and are subject to change. Always consult with a qualified financial advisor or CPA before implementing any strategy.